The UAE Golden Visa through property investment: what a broker must know before talking to the buyer
A property investor can obtain the UAE Golden Visa — a renewable 10-year residence — by owning one or more properties with a total value of at least AED 2 million, and the UAE government portal allows the property to be bought with a loan from specific local banks or off-plan from approved local developers. But the detailed conditions for mortgaged, off-plan and jointly owned property are set and updated by the competent authorities (ICP federally; in Dubai, GDRFA and the Dubai Land Department), so a broker should always point the buyer to the official source before making any promise.
Last updated:
What is the Golden Visa and why does it matter to brokers?
The Golden Visa is a long-term residence scheme the UAE introduced for groups including investors, entrepreneurs and talented professionals. For property investors it's a 10-year residence, renewable as long as the conditions still hold, with no need for a sponsor or employer, and the holder can sponsor family members under the conditions the authorities set.
For a broker, the Golden Visa isn't a side legal detail — it's a real buying motive. Many buyers, especially long-time residents and overseas investors, ask in the first conversation: "Will this unit qualify me for the Golden Visa?" A broker who knows the accurate answer — and the limits of what they know — earns the buyer's trust. One who promises what they can't deliver may lose both the deal and their reputation if the application is refused.
The broker's golden rule is simple: explain the general framework, help the buyer choose a unit clearly above the threshold, then refer them to the official authority or an approved service provider to confirm their case before paying. Never write "Golden Visa guaranteed" in an ad or message.
The core conditions for a property Golden Visa
The UAE government portal states that a property investor can apply for the Golden Visa by buying one or more properties worth at least AED 2 million. The threshold is measured by the property value as recognised by the emirate's real estate authority (the Dubai Land Department in Dubai), not the asking price in an ad. It can also be made up of more than one property, provided the total value meets the requirement.
The official portal also notes that the property can be bought with a loan from specific local banks, or off-plan from approved local developers. The fine details — such as a no-objection letter from the bank, the amount that must already be paid on a mortgaged or off-plan unit, and how each owner's share counts in joint ownership — vary by emirate and are updated from time to time. The table below summarises what a broker should verify in each case.
| Buyer's situation | General framework | What to verify officially |
|---|---|---|
| Ready property, fully paid | The clearest case if the value is AED 2M or more | The value recognised on the title deed or official valuation |
| Mortgaged property | Allowed with a loan from specific local banks | The bank letter required, and whether a minimum paid amount applies |
| Off-plan property | Allowed from approved local developers | Developer approval, contract registration, and the paid amount required |
| Several properties | Total value counts | That all properties are in the applicant's name and accepted together |
| Joint ownership | The applicant's share counts | Whether each owner's share must meet the threshold alone, and spouse cases |
Conditions change: how to handle updates
Property Golden Visa conditions have changed more than once since launch. Early press coverage cited AED 5 million with stricter rules for mortgaged property; the threshold then became AED 2 million with loans and off-plan allowed. In 2026 many property websites reported that the Dubai Land Department had eased the paid-amount conditions for mortgaged and off-plan units, but we could not find a published official text we can rely on for the details of that change, so we don't state its numbers here.
That's a clear example of why private websites — this article included — shouldn't be your final source. The right approach is for the broker to check current conditions on the UAE government portal, the Federal Authority for Identity, Citizenship, Customs and Port Security (ICP) and, in Dubai, the General Directorate of Residency and Foreigners Affairs (GDRFA) and the Dubai Land Department — and to note the date of the last check. When conditions change, update your messages and ads straight away.
- Review the official conditions at least monthly and record the date
- Don't copy numbers from social posts or unofficial websites
- If sources disagree, follow the government source and ask the buyer to confirm
- Outside Dubai, check with the local authority as procedures may differ
Documents and application steps in general
The document list and channels vary by emirate and property type, but the buyer usually needs proof of ownership and value, personal identity documents, and extra documents if the property is mortgaged or off-plan. The application goes through ICP's official channels, GDRFA in Dubai or approved service centres, and steps after approval can include a medical test, biometrics and issuing the Emirates ID. Fees vary by channel and the number of family members, so don't quote the buyer a fixed figure — point them to the fees shown on the official channel when applying.
- Title deed or registered sale contract (or the off-plan contract registered with the authority)
- Proof of the property's value if requested, such as an approved valuation
- A bank letter for mortgaged property, or a developer letter for off-plan, as officially required
- Passport, personal photo and Emirates ID if held
- Health insurance and medical test as the emirate requires
The broker's role: what to say and what not to say
A broker isn't a visa issuer or a legal adviser. Their role is to understand the buyer's goal, show units that serve it with a clear safety margin above the threshold, explain the general framework and refer the buyer to the official source. That approach protects you from complaints and protects the buyer from a decision based on wrong information.
Watch your ads too: advertising a specific unit in Dubai needs a Trakheesi advertising permit, and any Golden Visa wording in the ad must be accurate and not misleading. Write, for example, "unit value exceeds AED 2 million" rather than "gives you the Golden Visa". For the permit rules, see our Trakheesi and Madhmoun permits guide.
| Say | Avoid |
|---|---|
| "This unit's value is above the officially stated AED 2M threshold" | "The Golden Visa is guaranteed with this unit" |
| "Confirm current mortgage conditions with your bank and the authority" | "The loan never affects the visa" |
| "This developer is registered; check the authority accepts it for visa applications" | "Every off-plan project qualifies" |
| "Fees are shown on the official channel when you apply" | Quoting fixed fees from memory |
Work out the full cost before the buyer decides
A buyer targeting the Golden Visa sometimes focuses on the AED 2 million threshold and forgets the purchase costs themselves: registration fees with the land authority, brokerage, mortgage fees if any, valuation costs, then the residence fees. Give them the full picture from the start with the property buying costs calculator, and see Dubai's fees in detail in our DLD fees guide.
If the buyer is also an investor who wants rental income, work out the unit's net yield, because a high-value unit in a weak location might meet the visa threshold but disappoint on returns. The aim is a sound financial decision, with the visa as an added benefit on top.
Organising Golden Visa buyers in RabetCRM
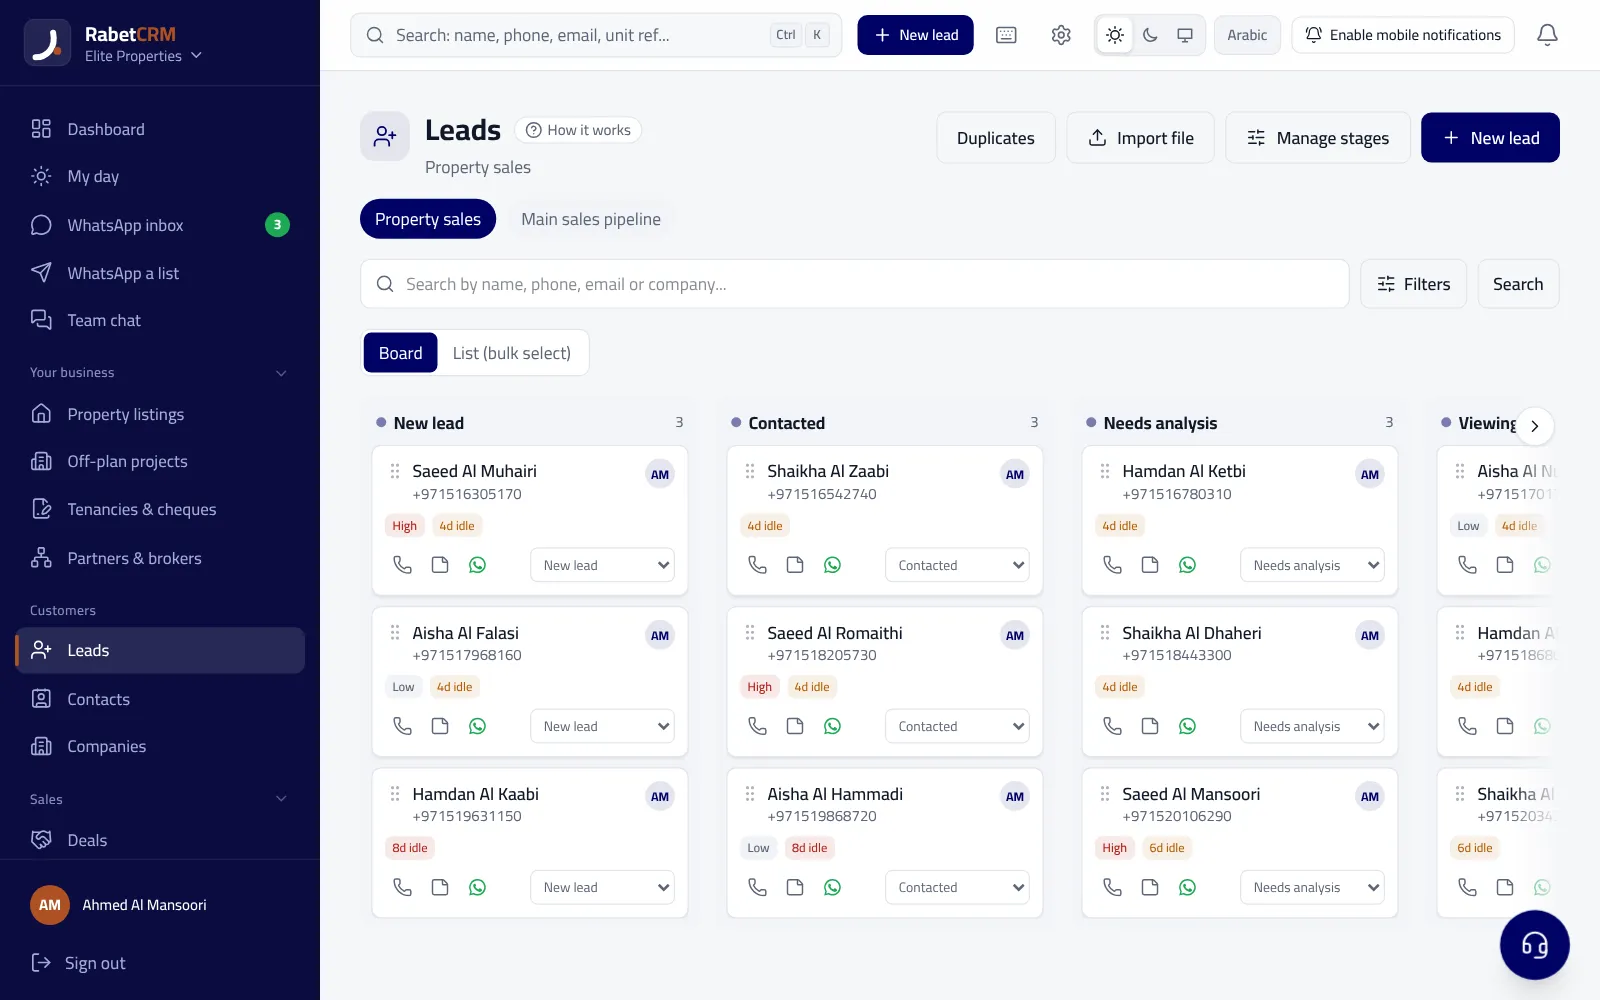
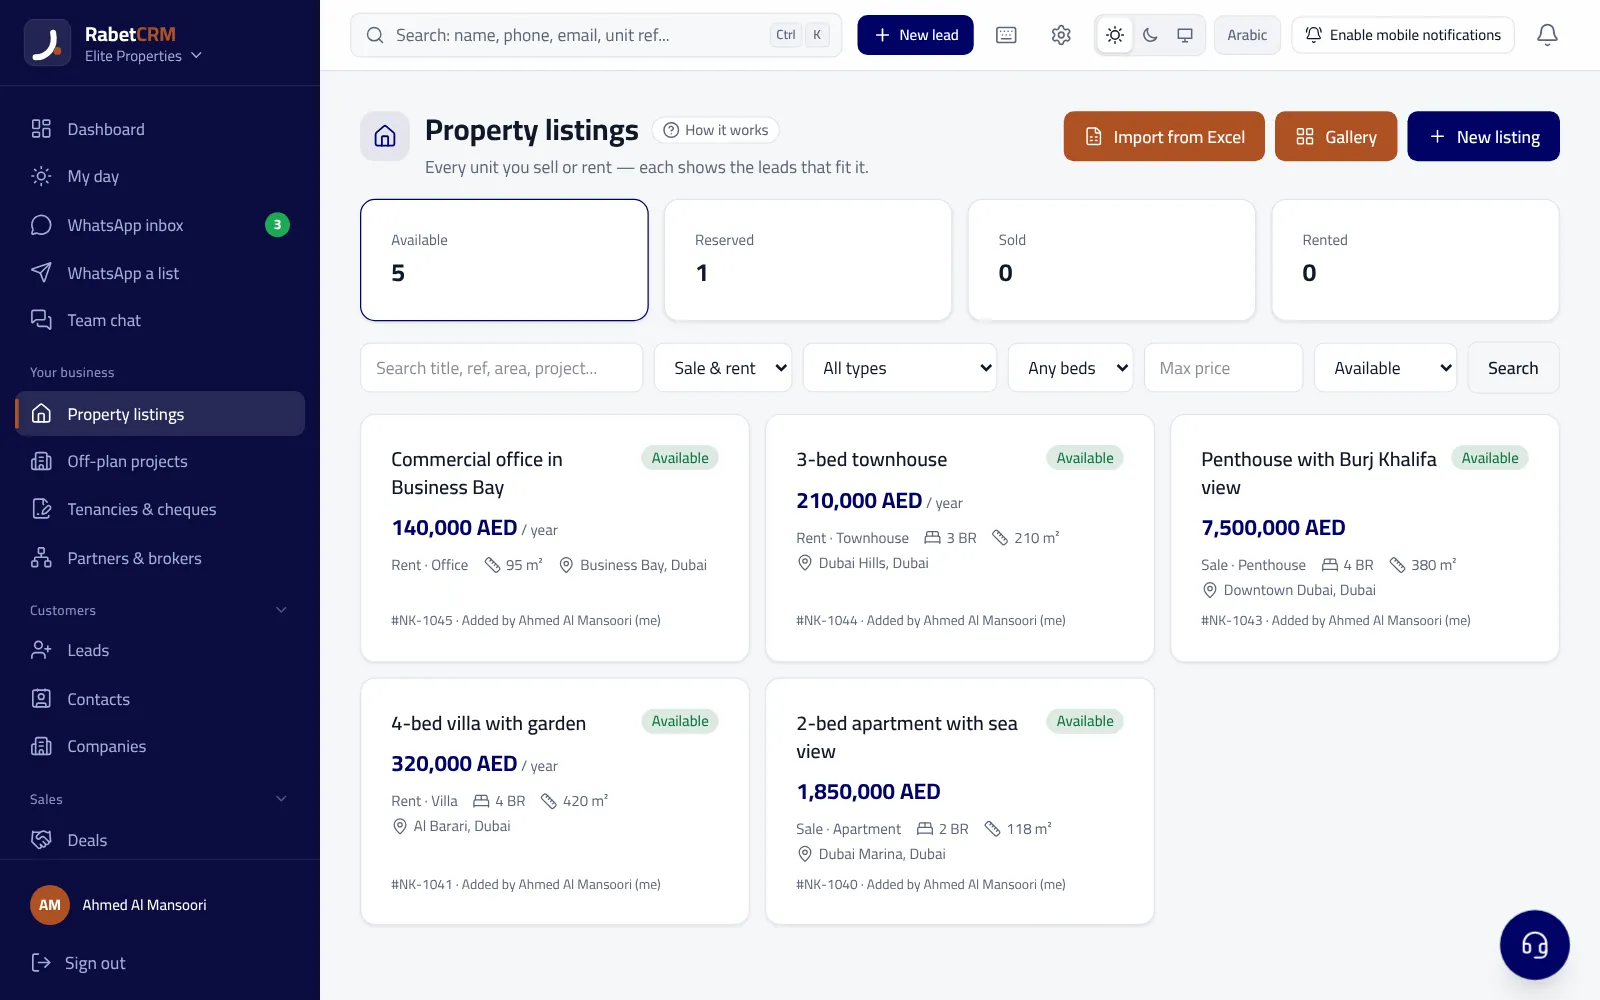
Golden Visa buyers are a segment with specific needs: a budget at or above the threshold, questions about mortgages and off-plan, and sometimes a longer decision cycle because they wait for official confirmation. In RabetCRM for real estate you record budget and interest on each lead, and use lead–listing matching to see the right units for each buyer and send them on WhatsApp in one tap. The lead hotness score shows who is actually engaging with the units you send.
If the deal is off-plan, the app tracks the payment plan and the buyer's installments automatically with reminders before each one, so you and the buyer know what's paid and what's left. Read more in our off-plan sales management guide, or start a 15-day free trial with no card.
More articles
Real estate CRM in every emirate
Compare RabetCRM
FAQ
What is the minimum property value for the Golden Visa?
The UAE government portal states the property or properties must be worth at least AED 2 million. Check current conditions with ICP, or GDRFA and the Dubai Land Department, before buying.
Can I get the Golden Visa with a mortgaged property?
Yes — the official portal allows property bought with a loan from specific local banks, but a bank letter is usually required and there may be conditions on the amount paid. These conditions have changed recently, so confirm them officially.
Does an off-plan property qualify for the Golden Visa?
It can, if bought from an approved local developer per the official portal, with extra conditions such as contract registration and amount paid that vary by emirate. Don't rely on a developer's or broker's promise; check with the authority.
How long is the Golden Visa for a property investor?
Ten years, renewable as long as the conditions still hold, and the holder can sponsor family members under the official conditions.
Can a broker mention the Golden Visa in a property ad?
You can state accurate facts such as the unit's value being above AED 2 million, but avoid phrases like "guaranteed visa", and make sure the ad carries the advertising permit the emirate requires.